


How to Find a Manufacturing Business For Sale in Ontario
If you’re considering diving into the world of entrepreneurship through acquisition, a manufacturing business for sale can be a smart investment. With a well-developed infrastructure, a highly competent labor force, and its location as a global trade center, Ontario provides an environment to pursue manufacturing industries in various sectors. Whether you are looking to buy a small manufacturing business for sale or take over a large-scale operation, knowing where and how to look can make all the difference.
Table of Contents:
Why Invest in a Manufacturing Business?
Manufacturing continues to play an important role in the world of economic growth and innovation. Investing in a manufacturing business for sale can offer:
- Existing Businesses operations – You can avoid the startup stage, and this provides you with a running operation that will have all equipment, employees, and clients.
- Predictable Revenue – This is because most manufacturing firms have long-term contracts or customers.
- Physical Assets – Buildings, equipment, and stock are contributors to the resale value of the business.
The manufacturing sector ranges from packaging, electronics, and food processing, among others, in the sense that it can suit various appetites for investments.
Where to Find Manufacturing Businesses for Sale
Finding a good business to own can be a case of research, endurance, and, in most cases, it is through networking. These are methods that have been proven to start your search:
- Online Business Marketplaces
There are so many websites where you can filter businesses by price, location, and industry. Look specifically under “Business for Sale Manufacturing” categories for tailored results.
- Local Business Brokers
Specialized brokers usually get access to nonpublic listings. It is also possible to help them with valuation and negotiation.
- Industry Networks and Events
Insider opportunities often show up at trade shows and through local manufacturing associations. Networking remains a powerful tool in discovering a small manufacturing business for sale.
- Word of Mouth and Private Listings
Other owners do not like to go public. Make it known to your professional contacts that you are available and in the market.
What to Note Before Purchasing
Not all businesses on sale are good deals. Ensure that you do a due diligence, taking into consideration:
- Financial Health – Look into the financial statements, tax records, and the cash flow.
- Used Equipment Condition– Evaluate whether the equipment is old and outdated or whether it should be replaced.
- Licensing and Compliance – Ensure that the business is licensed and complies with the local and federal regulations.
- Market Demand – do the products have an increasing or steady demand in the market?
- Scalability – Is the expansion of the operation with minimum investment possible?
This will influence your investment decision as well as the smoothness of transition once you have purchased it.
Spotlight: Manufacturing Business For Sale Ontario
Ontario in Canada is another region that you should consider in case you are venturing outside Ontario. Ontario is also the holder of a robust manufacturing capability, as well as numerous similarities with regard to expertise, infrastructure, and economic facilities to production companies. Whether you’re looking in Ontario or considering a manufacturing business for sale in Ontario, the principles of due diligence and strategic fit remain the same.
The Option of Buying vs. Starting a Small Manufacturing Business

It is not a small task to start a business from scratch. Here’s why buying an existing small manufacturing business for sale might be the better route:
Pros of Buying a Business:
- Immediate customer, employee, and network of suppliers access
- Quicker ROI with available revenue
- Financing is easier with cash flow that has been demonstrated
Cons of starting a business from scratch:
- An increase in risk where there is no presence in the marketplace
- It may take a long time to set up
- Doubt concerning profitability and demand
Acquiring a business is also beneficial since you have the operating model that you are able to perfect as compared to starting at ground zero.
Selling A Manufacturing Business
If you’re on the other end of the transaction and considering selling a manufacturing business, preparation is key:
- Valuation – Enlist the services of professionals to value assets and determine the worth of the business.
- Documentations – Prepare any license, financial documents, and contracts.
- Exit Plan – Be familiar with what you will be engaged in after the sale.
- Brokerage Help – A broker will be able to handle enquiries and filter the serious buyers.
An effective exit strategy can maximize its returns, and the business can continue to flourish with the new ownership.
Watch Out for Red Flags
As with any business acquisition, be alert to possible problems:
- Legal Troubles – Pending lawsuits or compliance violations
- Inflated Financials – Unrealistic, or overly optimistic projections
- Customer Concentration– Highly dependent on a single or two customers
- Outdated Equipment – The cost of replacement can be very high
These red flags can be figured out in the course of a due diligence through the help of a professional advisor.
Final Thoughts
The process of acquiring a manufacturing business will begin through prepared decisions and realistic hopes. Whether you’re scouting a small manufacturing business for sale or considering a larger-scale industrial opportunity, the same fundamentals apply: research, professional advice, and a clear understanding of what you’re buying.
And don’t forget—if you’re selling a manufacturing business, the steps you take to prepare today will shape the success of your sale tomorrow.
A manufacturing business is like an entry point to financial freedom and future prosperity in an active market like Ontario, an industrial town like Ontario, etc., if you choose it well.
Take your time, ask the right questions, and strike when you are ready.
Read More
How to Sell Your Distribution Business for Maximum Value
In today’s globalized economy, Canada imports a wide range of goods from around the world—making distribution businesses a highly profitable sector.
Why are distribution businesses so popular?
- No specialized knowledge required
- Low barriers to entry
- Minimal investment, high return potential
Table of Contents:
- Types of Distribution Businesses
- The Distribution Business in Canada Comprises Many Things:
- To Achieve the Highest Possible Return, Keep These Strategic Steps in Mind:
- How to Assess a Distribution Business for Sale in Canada
- Preparing for the Sale
- How to Accurately Determine the Value of Your Distribution Business
Types of Distribution Businesses
- Retail Distributors: These businesses sell products directly to consumers, often through brick-and-mortar stores or online platforms.
- Wholesale Distributors: They supply goods to retailers or other businesses and are typically located in urban centers.
- Direct Channel Distributors: These distributors bypass intermediaries to sell directly to consumers, similar to wholesale models but with a customer-facing focus.
- Indirect Channel Distributors: These use intermediaries—like agents or brokers—to deliver products to the end user. This is another widely used and effective distribution model.
Are you running a distribution business? Thinking of selling? Want to maximize your profit?
Keep reading to discover how to sell your distribution business for top dollar.
The Distribution Business in Canada Comprises Many Things:

- Warehousing: Store products in a centralized, strategic location—ideally close to the final delivery point. This helps minimize transit time and streamline fulfillment.
- Inventory Management: Maintain optimal stock levels to prevent shortages or overstock. Effective inventory control ensures smooth operations and satisfied customers.
- Transportation: Coordinate the movement of goods from suppliers to warehouses and retailers, or directly to end customers. Reliable logistics are essential.
- Order Processing: Efficiently manage customer orders—from receipt to fulfillment. Fast, accurate processing builds trust and drives repeat business.
- Shipping and Delivery: Ensure timely and accurate delivery to customers or retailers. Speed and reliability are key differentiators in a competitive market.
- Return Management: Handle product returns and exchanges with professionalism. A smooth returns process enhances customer satisfaction and brand loyalty.
- Customer Service: Provide responsive, knowledgeable support for all stakeholders. Most customer service inquiries relate to shipping, order status, and supply chain concerns.
- Relationship Building: Foster strong, long-term partnerships with retailers, suppliers, and logistics providers. Solid relationships are the backbone of distribution success.
- Financing: Manage cash flow and credit effectively. Financial stability allows for growth, timely payments, and operational flexibility.
To Achieve the Highest Possible Return, Keep These Strategic Steps in Mind:
- Assess Your Strengths and Weaknesses: Gain a clear understanding of what sets your business apart and areas for improvement. This will help you present a realistic and compelling case to buyers.
- Identify Your Target Buyer: Know who your ideal buyer is. Are you targeting industry players, investors, or entrepreneurs? Tailor your messaging to align with their interests and priorities.
- Determine the True Value of Your Business: Conduct a professional valuation to establish an accurate market value. Consider
financial performance, growth potential, customer base, operational efficiency, and market trends.
How to Assess a Distribution Business for Sale in Canada
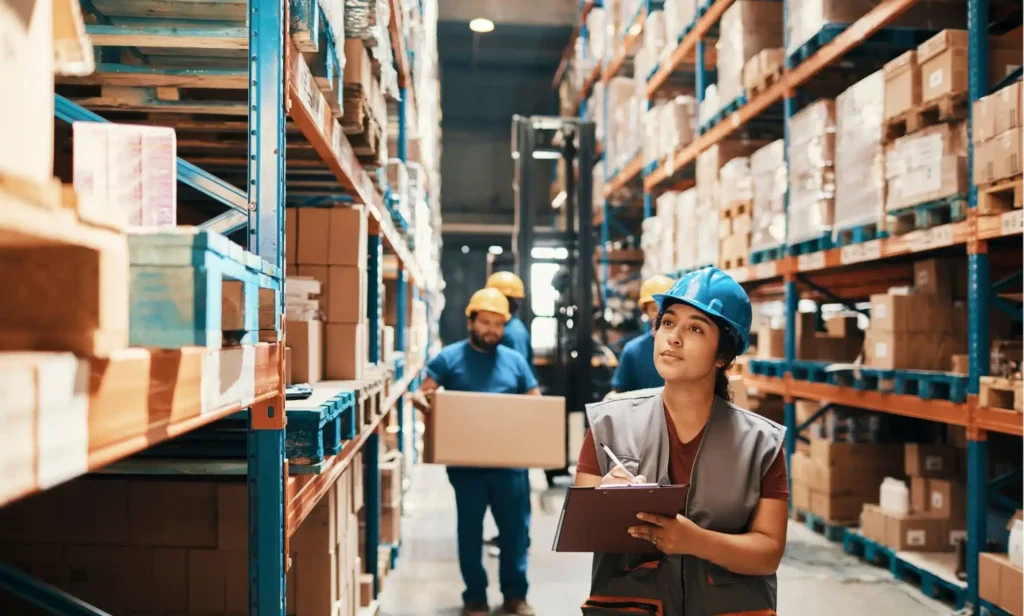
A detailed guide to preparing your business for a successful sale
Before listing your distribution business for sale, it’s crucial to evaluate its key assets and position in the market. Here are the essential steps:
- Evaluate Your Product Line: Ensure you have a clearly defined and market-relevant product offering. A strong product line is one of your most valuable assets. Conduct thorough market research to understand current demand, competition, and opportunities for future growth.
- Analyze Your Customer Base: Your customer base is arguably your greatest asset. Assess customer demographics, loyalty, and retention rates. Strengthen relationships and maintain high satisfaction levels to enhance the perceived value of your business.
- Review Existing Contracts: Examine all supplier agreements and contracts. Are they favourable? Can they be transferred to a new owner? Buyers will be particularly interested in secure, long-term supplier relationships that provide operational stability.
Preparing for the Sale
- Identify Potential Buyers: Understand what type of buyer your business will attract—industry operators, investors, or entrepreneurs. Tailor your marketing strategy to speak directly to their motivations and goals.
- Study Market Trends: Stay informed about industry shifts such as the rise of e-commerce, evolving consumer behavior, and changes in supply chain logistics. Demonstrating awareness and adaptability to these trends makes your business more appealing to buyers.
Taking the time to thoroughly assess these factors can significantly boost your business’s value and increase your chances of a successful sale.
How to Accurately Determine the Value of Your Distribution Business
Valuing your distribution business correctly is critical to attracting serious buyers and maximizing your return. Here’s how to do it right:
- Revenue and Profitability: Provide accurate and detailed financial data, including revenue, gross profit, and net profit. Assess both current performance and future earning potential. This is essential for demonstrating the financial health and sustainability of your business.
- Market Valuation: Analyze current market conditions and comparable business sales to determine your fair market value. Understanding industry benchmarks will help you price your business competitively and realistically.
- Intangible Assets: Don’t overlook intangible assets—such as brand reputation, customer loyalty, proprietary systems, or supplier relationships. These unseen elements can significantly influence the overall value of your business.
- Marketing and Sales Positioning: Create a compelling business profile that highlights your strengths. Support it with a professional website, clear financials, and a valuation report. A well-presented business stands out to potential buyers and gives you a competitive edge.
- Networking and Relationship Building: Leverage your network to identify potential buyers. Reach out to industry associations, business brokers, and professional contacts. These relationships can be instrumental in finding the right buyer and closing the deal faster.
- Legal and Regulatory Compliance: Ensure your business complies with all applicable laws, especially in areas like distribution, sales, and employment. Work closely with legal counsel to protect your interests and avoid any obstacles during the sale process.
The Critical Role of Confidentiality in Business Sales

When it comes time to sell a business, ensuring confidentiality should always be the top priority. A breach of confidentiality is one of the quickest ways to undermine a business sale. Once this trust is broken, it can be incredibly difficult to contain or fix the resulting damage. This rule applies universally, regardless of the type of business or industry.
Experienced attorneys, accountants, business brokers, and M&A advisors all prioritize maintaining confidentiality for good reason. A single lapse can have far-reaching consequences, potentially devastating a business or severely affecting its market value. Even if a breach doesn’t lead to complete destruction, it can tarnish the company’s reputation and significantly reduce its worth.
The risks that arise once news of a sale becomes public are substantial. Key employees, customers, and suppliers may begin to look for alternatives, assuming that the sale will lead to disruptions. The loss of even one key person or relationship can end up destabilizing the business. Employees might start to worry about their future within the company and begin seeking other job opportunities. In the worst-case scenario, they may take their expertise to a competitor, weakening your business in the process.
Another issue that can arise is that management-level employees, whose experience is critical to the company’s operations, might leave. Of course, it goes without saying that this issue likely will create a gap that is difficult to fill, especially if you’re trying to do it quickly. Similarly, valuable customers and suppliers could seek more stable alternatives. These changes can have an immediate negative effect on the company’s bottom line and cause its value to decrease.
Perhaps even more worrisome is the risk posed by competitors. If your competitors learn that your business is for sale, they might not hesitate to share this information with your customers and suppliers, further tarnishing your market position. They may even intensify their efforts to win over your clients.
It cannot be underestimated why confidentiality is so important to the sale process. A breach can undermine your ability to close the deal successfully. Experienced business brokers and M&A advisors are trained to protect confidentiality at every stage of the sale. They go beyond simply having potential buyers sign non-disclosure agreements. They also carefully vet buyers to ensure they are genuinely interested, not just collecting information or “window shopping.”
By working with qualified brokerage professionals, you gain an added layer of protection for your business’s confidentiality. Ensuring that only serious buyers are involved in the process helps to safeguard the value and reputation of your business. The complexities of selling a business are many, but protecting confidentiality remains the most fundamental step in achieving a successful sale.
Copyright: Business Brokerage Press, Inc.
The post The Critical Role of Confidentiality in Business Sales appeared first on Deal Studio.

3 Meeting Tips for Buyers and Sellers in Business Transactions

When buying or selling a business, the initial meeting between the buyer and seller can be a critical turning point. This meeting often sets the stage for the future of the deal. After all, the buyer’s first offer typically arrives right after this pivotal discussion. Ensuring that the conversation is positive, professional, and productive is crucial for both parties involved. Business brokers and M&A advisors play an essential role in preparing both buyers and sellers to navigate these discussions successfully.
Table of Contents:
For buyers, it’s important to have a clear understanding of how the selling process works and what to expect during the meeting. Heeding the advice of their broker is key, as it helps maximize the chances of favorable outcomes.
On the seller’s side, transparency is vital. Sellers should aim to be open and honest without being too heavy-handed. A balanced approach that fosters trust is far more likely to yield results.
Ask Thoughtful Questions
For buyers preparing to meet with a business owner, it’s important to ask relevant questions. A buyer who asks well-researched and meaningful questions will demonstrate a genuine interest in the business. This not only builds credibility but also helps establish a foundation for mutual respect.
Buyers should come to the meeting prepared. They should be sure to do their homework in advance. This can mean everything from reviewing financials and gaining an understanding of the industry to identifying potential risk. These actions will help create a positive impression and lay the groundwork for a productive conversation.
Build A Rapport
Throughout the meeting, buyers should maintain a polite, respectful demeanor. It’s best to steer clear of controversial topics like politics or religion, as these can easily lead to unnecessary conflict. The goal is to foster a relationship based on trust and professionalism. If a seller doesn’t like or trust a buyer, it could create obstacles that prevent the deal from moving forward.
Sellers often view their business as a personal legacy, a culmination of years or even decades of hard work. This emotional attachment means that buyers should approach the meeting with a degree of sensitivity. They should understand that the business represents more than just a financial transaction. A failure to acknowledge the seller’s emotional investment could harm the relationship and that could lead to jeopardizing the deal.
Embrace Honesty
While sellers are seeking to sell their business, they should avoid presenting themselves as overly sales-focused. Buyers appreciate authenticity and transparency, so sellers should strive to present their business honestly. That means sharing both its strengths and its challenges.
It’s also essential for sellers to acknowledge the competitive landscape. Every business faces competition, and attempting to downplay or ignore this reality will likely raise red flags. A truthful approach is far more likely to foster trust and lead to a successful transaction.
The Role of Brokers and Advisors
Ultimately, business brokers and M&A advisors are invaluable throughout this process. They guide both buyers and sellers in preparing for the meeting and help set realistic expectations. By working closely with both parties in advance, brokers ensure that the discussion is as constructive as possible, improving the likelihood of a positive outcome. With proper preparation and expert guidance, both sides are more likely to walk away with a successful agreement.
Copyright: Business Brokerage Press, Inc.
The post 3 Meeting Tips for Buyers and Sellers in Business Transactions appeared first on Deal Studio.
How to Successfully Sell Your Distribution Business in Canada
The distribution industry is vital to Canada’s economy, making it a thriving and competitive space for business owners and investors. If you’re a distribution business owner in Ontario considering a sale, whether planning for retirement, looking to capitalize on your success, or simply ready for a new chapter, knowing how to navigate the selling process is essential to achieving a smooth and profitable transaction.
Table of Contents:
In this blog, we will guide you through everything you need to know about selling your distribution business. From preparing your business for sale and attracting qualified buyers to understanding what makes your business stand out in today’s market, we’ve got you covered.
What Is a Distribution Business?
A distribution company ships products from one place to another. You do not manufacture the products; you help deliver them to the customers who need them. For instance, you might go pick something up from a factory and send it to shops, or sell machines and gear to institutions. If you are distributing equipment or machinery to businesses such as factories or construction companies, you are an industrial equipment distributor. Such businesses are very significant and can be very lucrative.

Why Sell Your Distribution Business?
There are so many reasons why owners decide to sell their Distribution businesses, the most common of which are:
- Retirement or lifestyle changes
- Shifting to a new business
- market conditions
- acquisition opportunities from large companies
No matter what the reason is, planning everything strategically can help ensure you get the best outcome.
Understanding the Value of the Distribution Business
The distribution industry plays a vital role in the supply chain, serving as the critical link between manufacturers and retailers or end users. Whether it’s food and beverage distribution or industrial equipment, the sector includes a wide range of specialized niches.
For buyers, distribution businesses are an attractive investment thanks to several key advantages:
- An established customer base
- Consistent, reliable revenue streams
- Valuable relationships with suppliers and vendors
If your business operates within a niche, such as distributing industrial machinery, you may be able to command a premium price. This is especially true if you hold exclusive supplier agreements or cater to a specific, in-demand market.
So, how can you prepare your distribution business for a successful sale? Let’s explore the key steps to get your business ready and make it stand out to serious buyers.
Before you officially put your distribution business on the market, it’s important to get everything in order. Here’s a step-by-step guide to help you prepare for a successful and profitable sale:
1. Organize Your Financial Records
Buyers want transparency and confidence in your numbers. Ensure your financial records are accurate, up-to-date, and easy to understand. Have at least two to three years of financial statements readily available – this includes income statements, balance sheets, and cash flow reports. Clean, well-organized books build trust and can speed up the sales process.
2. Streamline Your Operations
A business that runs smoothly without the owner’s constant involvement is far more attractive to buyers. Document your daily operations, procedures, and workflows. Make sure your team is well-trained and your systems are efficient – this demonstrates stability and reduces perceived risk for potential buyers.
3. Highlight What Makes Your Business Valuable
Do you have exclusive distribution rights, specialized equipment, or long-term contracts with loyal customers? Identify and highlight the key assets that set your business apart. These are the elements that can justify a higher valuation and attract more serious buyers.
4. Define Your Unique Selling Points
What makes your distribution business stand out from the rest? Whether it’s a niche market, strong vendor relationships, or a loyal customer base, make sure to communicate your unique advantages. A buyer will always ask: “Why this business over another?” – so be ready with a compelling answer.
What Buyers Are Looking For?
Most buyers are drawn to distribution businesses that are already running smoothly. They’re looking for consistent revenue, a loyal customer base, and clear potential for future growth. To secure the best possible price, make sure your finances are in order, your operations are streamlined, and you can clearly articulate what sets your business apart.
Keep your marketing simple and searchable – using a headline like “Distribution Business for Sale Ontario” can help serious buyers find you quickly online. If you’ve built solid systems and have a capable team in place, that adds serious value. Buyers are also more inclined to invest when they see opportunities to expand, whether by adding new products, entering new markets, or growing the customer base.
Assist the New Owner in the Transition
Selling your distribution business doesn’t end with signing on the dotted line. One of the most valuable steps you can take is to support the new owner through a smooth transition. By agreeing to stay on for a short period post-sale, you can help them understand day-to-day operations, introduce them to key customers and suppliers, and ensure continuity in the business.
This kind of transition support provides reassurance to the buyer, helps employees and clients adjust to the change, and reinforces the stability and value of your business. It shows that your company isn’t just profitable – it’s well-run, well-respected, and built to last.
Conclusion:

Selling your distribution business in Canada, especially in a high-demand market like Ontario, can be a smart and rewarding decision. Whether you specialize in industrial equipment, consumer goods, or another niche, there are serious buyers actively seeking well-established companies like yours.
To make the process smoother and more successful, consider working with experienced business brokers, such as the team at Ontario Commercial Group. They can connect you with qualified buyers, manage the details, and help maximize your sale price, taking much of the stress off your shoulders.
With the right plan and expert guidance, selling your business can be a simple, profitable experience and a major milestone on your journey to whatever comes next.
Read More
Franchise Business Opportunities: What They Are and How To Get Started?
While looking for franchise business opportunities in Toronto, you should remember many scenarios, like what your business interests are and what type of business you are looking for. If you do not understand the business requirements and terms, in the future, you can face problems in your work. Choose what encourages you to work and go ahead with the best franchise opportunities; take advice from professional business brokers, M&A, and advocates for understanding legal documentation and negotiating the deal.
Read More
Key Considerations Before Buying A Business

When considering the purchase of a business, asking the right questions is essential. Whether you’re a first-time buyer or a seasoned entrepreneur, you’ll want to avoid unpleasant surprises down the line. One way to do that is to be proactive and diligent when you’re making your evaluations. Below are some critical areas to explore before signing any agreements.
First, it’s important to understand the current challenges that the business you’re interested in may be facing. Every business has its pain points. By asking the seller to share these openly, you can better prepare for potential hurdles. Gaining insight into any prospective difficulties can also shed light on areas where you might be able to improve operations or take advantage of opportunities for growth.
Another important consideration is to ensure financial transparency in the transaction. Sellers should provide comprehensive and accurate financial details, including profit margins, revenue streams, and expenses. Transparent financial information allows buyers to make informed decisions, assess the true value of the business, and identify any potential risks. By demanding financial transparency, you can ensure that the business’s valuation is accurate and justified, which is crucial for establishing trust and confidence in the transaction.
Along with financials, it’s obviously essential to examine the business’s legal standing. You should inquire about any past, current, or potential lawsuits that might be attached to the business. Legal issues can have long-term implications, so it’s essential to know if there’s any risk of future complications. Don’t assume that you’ll find out about these kinds of issues if you don’t do due diligence.
The business’s operations are also worth scrutinizing. It will help you a great deal to learn how day-to-day operations are documented. This information can help you assess how smoothly you can take over. If the business in question has clear and organized procedures, this will help make the transition easier. Additionally, you’ll want to evaluate how much the business relies on specific vendors or customers. If a significant portion of revenue depends on one source, this could pose a risk if circumstances change.
A business should align with your strengths to ensure long-term success. That’s why you’ll want to have a firm grasp of the skills and experience needed to run the business. This information will help you understand whether you really are the right fit for the business or if there are areas where you might need additional support.
Finally, it’s important to have a clear picture of the workforce. Will key employees stay with the company? Employee stability is vital for maintaining the ongoing success of the business after you take over.
Asking thorough questions and gaining a deep understanding of the business will empower you to make an informed decision. The more you know about the challenges and opportunities, the better prepared you will be to navigate the acquisition successfully. Every business has some risks, so it’s your job to find out what they are. By being diligent, you reduce the likelihood of headaches down the road. Asking questions proactively will help you reach greater levels of success.
Copyright: Business Brokerage Press, Inc.
The post Key Considerations Before Buying a Business appeared first on Deal Studio.

A Simple Guide to Business Brokers for Ontario Manufacturing Businesses
If you’re looking to buy or sell a business—especially a manufacturing business—you’ll likely benefit from the expertise of a business broker. A skilled broker simplifies the process by connecting buyers and sellers, negotiating favorable terms, and guiding both parties through the complexities of the transaction.
Table of Contents:
In Ontario, working with an experienced business broker can make all the difference. They understand the market, maximize deal value, and ensure a smooth transaction. This is particularly crucial when dealing with manufacturing businesses, where industry knowledge and strategic positioning can significantly impact the outcome.
What Does a Business Broker Do?
Business brokerage operates much like an intermediary, connecting business owners looking to sell with qualified buyers seeking the right investment. Top business brokers in Ontario, such as Ontario Commercial Group, bring extensive industry knowledge and expertise, streamlining the process while proactively addressing potential challenges.
For example, if you’re selling a manufacturing business, a specialized manufacturing business broker can assist with:
- Identifying the most suitable buyers
- Setting a competitive and fair valuation
- Managing all necessary paperwork
- Negotiating favorable terms on your behalf
With their guidance, both buyers and sellers can navigate the complexities of a business transaction with confidence. Business brokers in Ontario not only help match sellers with the right buyers but also ensure a seamless and successful deal.
Why Use a Business Broker?
If you’re planning to buy or sell a manufacturing business, working with a business broker can make the process smoother and more profitable. Here’s why:
- Market Expertise
Business brokers in Ontario have a deep understanding of market trends, business valuations, and buyer expectations. They ensure sellers price their business competitively and help buyers secure a fair deal. - Paperwork Management
Buying or selling a business involves extensive documentation. A business broker handles all necessary paperwork, ensuring accuracy and compliance with regulations. - Protecting Your Interests
A skilled broker works to secure the best possible deal for you. If you’re selling, they negotiate for maximum value. If you’re buying, they identify potential risks and ensure you make an informed decision. - Access to a Vast Network
Brokers have an extensive network of qualified buyers and sellers, allowing them to connect the right people quickly and efficiently. - Specialized Local Knowledge
Ontario’s manufacturing sector is thriving, and local business brokers specialize in navigating its unique landscape. Whether you’re dealing with a small or large manufacturing business, they streamline the process, saving you time and effort.
By leveraging their expertise, connections, and industry knowledge, Ontario business brokers help buyers and sellers achieve smooth and successful transactions.
Role of M&A Advisors

When dealing with large and complex business transactions, hiring M&A (Mergers and Acquisitions) advisors is often essential. These specialists are experts in managing high-value deals, including mergers, acquisitions, and the sale of sizable businesses. While business brokers typically handle smaller transactions, M&A advisors bring in-depth financial expertise and strategic insight for more intricate deals.
In the case of manufacturing businesses for sale, M&A advisors play a crucial role—especially when the business is a large-scale operation, such as a major manufacturing plant with significant assets and a sizable workforce. They work alongside business brokers to ensure a seamless, well-structured transaction, maximizing value while minimizing risks.
How a Business Broker Helps Manufacturing Business Buyers
If you’re looking to purchase a manufacturing business for sale, a specialized manufacturing business broker can guide you through every step of the process:
- Finding the Right Business – A broker identifies manufacturing businesses that match your requirements, industry preferences, and budget.
- Business Evaluation – They assess the business’s financial statements, equipment, operations, and overall viability to ensure it’s a sound investment.
- Negotiating a Fair Price – Brokers leverage their expertise to negotiate a competitive price, protecting your interests.
- Simplifying the Process – From handling paperwork to ensuring a seamless closing, brokers take care of the legal and administrative details, making the transaction stress-free.
How A Business Broker Helps Sell A Manufacturing Business

If you’re looking to sell your manufacturing business, a business broker can ensure you get the best deal by:
- Finding Qualified Buyers – Brokers connect you with serious buyers willing to pay a fair price for your business.
- Setting the Right Price – They analyze market trends and business performance to determine an accurate and competitive valuation.
- Handling Negotiations – Brokers manage all discussions with buyers, ensuring you secure the highest possible price while maintaining confidentiality.
- Managing the Sale Process – From paperwork to legal formalities, they oversee every detail, ensuring a smooth and hassle-free transaction.
Whether you’re buying or selling, working with an experienced manufacturing business broker ensures you get the best value while avoiding common pitfalls.
Conclusion
No matter the reason for buying or selling a manufacturing business, having an experienced business broker by your side can make all the difference. They handle the complexities of the transaction, ensuring you secure the best possible deal with minimal stress.
If you’re in Ontario, local business brokers can connect you with the right buyers or sellers, matching you with serious prospects who are genuinely interested in a business like yours. For larger or more intricate deals, M&A advisors provide specialized expertise, helping you navigate high-value mergers and acquisitions.
A manufacturing business broker streamlines the entire process, leveraging their industry knowledge to guide you every step of the way. From valuation and negotiations to paperwork and finalizing the deal, they ensure a smooth, efficient, and successful transaction—right from the first step to the final handshake.
Read More
Selling Your Business? Consider These 5 Things First
Selling a business in Canada is one of the most challenging decisions a business owner can face. Whether driven by personal or professional reasons, deciding to sell your business is not a decision to be taken lightly. While the future may be uncertain, it’s essential to evaluate your current situation carefully before taking a significant step like selling your business in Ontario.
Table of Contents:
This process goes beyond merely transferring ownership—it requires a deep understanding of your motivations and meticulous attention to the legal and procedural details involved. In this blog, we’ll explore why selling your business can be a time-intensive journey and highlight the key considerations you should keep in mind throughout the process.
5 Things You Must Consider While Selling Your Business in Ontario

When selling your business in Ontario, there are several key factors to keep in mind. From accurately valuing your business to ensuring all legal aspects are covered, and from selecting the right broker to finding the ideal buyer—each step plays a vital role in a successful sale. Here are five essential points to consider:
1. Evaluate Your Business Value
Begin by determining the true value of your business. This requires in-depth market research, an analysis of current trends, and a comprehensive review of your financial performance—including assets, liabilities, revenue, and profit margins. A professional business broker can be invaluable in helping you arrive at an accurate valuation.
2. Organize Financial Records
Transparency is key. Prospective buyers will expect easy access to well-organized financial documents, such as tax returns, financial statements, and other relevant records. Ensuring these documents are accurate and readily available—and even undergoing an audit—can significantly enhance credibility and attract serious buyers.
3. Enhance Business Operations
Optimizing your operations can boost your business’s value and appeal. Streamline processes, improve efficiency, and clearly demonstrate your company’s financial health. By showcasing a well-managed operation and a solid plan for the future, you can instill confidence in potential buyers and facilitate a smoother transition post-sale.
4. Develop a Comprehensive Business Plan
A detailed business plan is essential when selling your business. It should outline your business model, market position, growth strategy, and competitive landscape. This plan not only serves as a roadmap for the future but also provides potential buyers with the insight they need to see the long-term value and potential of your business.
5. Seek Professional Guidance
Navigating the sale process can be complex. Engage with experienced professionals such as business brokers, M&A advisors, financial consultants, and legal experts. Their expertise will help ensure that your documentation is in order, that you understand every aspect of the sale, and that you negotiate the best possible deal.
By keeping these five points in mind, you can approach the sale of your business in Ontario with confidence and clarity, ensuring a smooth and successful transition.
Conclusion
Before taking the first step toward selling your business, it’s essential to clearly understand its value and financial standing. Knowing your business’s worth not only helps you set the right price but also instills confidence in potential buyers, who are keenly interested in its future growth and financial health. To ensure that all your documents and operational processes are in perfect order, consider seeking guidance from experienced M&A advisors. Every stage of the selling process is crucial, so meticulous preparation is key to a successful sale.
Read More
3 Steps to Sell Your Business Quickly and Efficiently
Before delving into the specific steps that benefit business owners who are looking to sell quickly, it’s crucial to understand the buyer’s viewpoint. For many buyers, purchasing a business is a once-in-a-lifetime event, often involving significant personal and financial risk. Therefore, sellers must take proactive steps to ensure their business is as appealing and risk-free as possible.
There are 3 Key Areas to Focus On for a Successful Exit:
- Step 1: Prioritizing Pre-Diligence
- Step 2: Reducing Perceived Risk
- Step 3: Engaging the Right Professionals
By focusing on these areas, you can instill buyer confidence while increasing the likelihood of a smooth transaction.
Step 1: Prioritizing Pre-Diligence
The first step to preparing a business for sale is to view the process from the buyer’s perspective. Buyers will conduct due diligence to assess the financial health, legal standing, and overall stability of the business. If you are able to anticipate and address potential issues beforehand, you can streamline the process.
Well in advance, business owners should work with qualified professionals to ensure that all documentation is in order, financials are accurate, and the business complies with all relevant regulations. This pre-diligence process will create fewer hurdles during the buyer’s due diligence and provide a smoother transition to closing the sale.
Step 2: Reducing Perceived Risk
One of the most effective ways to make a business more appealing to buyers is to minimize perceived risks. Buyers are naturally cautious about purchasing a business, and any factors that raise concerns can hinder a sale.
Here are a few areas where sellers can reduce risk before listing:
- Revenue Concentration: If the business is overly reliant on a few key clients or customers, consider diversifying the customer base or developing long-term contracts that mitigate this risk.
- Employee Contracts: Secure and well-structured employee agreements can provide stability and reassure buyers that the business has a reliable workforce.
- Clear Customer Contracts: Well-drafted and easy-to-understand customer agreements can reduce legal uncertainties and increase buyer confidence.
- Addressing Legal or Financial Liabilities: If there are outstanding legal issues, potential liabilities, or financial discrepancies, it’s wise to resolve these before listing the business.
By addressing these concerns in advance, sellers can significantly increase how attractive buyers will perceive their businesses to be.
Step 3: Engaging the Right Professionals
The right team of professionals can make all the difference when selling a business. Business brokers, M&A advisors, accountants, and legal experts help guide sellers through the complexities of the sale process. They can assist with everything from developing an exit strategy to ensuring that the sale adheres to all legal and financial standards.
Engaging professionals early in the process ensures that the seller has the right advice and support to navigate negotiations, minimize risk, and maximize the business’s value. These experts can also help identify and address potential red flags that might otherwise hinder the sale.
Copyright: Business Brokerage Press, Inc.
The post 3 Steps to Sell Your Business Quickly and Efficiently appeared first on Deal Studio.
Read More