



Thriving in the Modern Business World

As we step further into the 21st century, the landscape of business is changing. While there are always new challenges on the horizon, the core principles of achieving success in business remain largely unchanged. Have you considered how well you’re preparing for both the new and enduring demands of entrepreneurship? Let’s take a look at some standards to abide by.
Table of Contents:
Are You Embracing Technology?
The digital age has transformed how businesses operate. This is something you need to be thinking about constantly, whether it’s marketing or the nature of transactions. Entrepreneurs today must harness technology to engage customers directly, often through digital platforms instead of traditional print, radio, or TV advertising. This technological shift is not just a trend—it’s the future. Of course, that means that those who fail to adapt risk falling behind.
Can You Adapt?
The market is always shifting, and products or services that seem promising today could quickly lose relevance tomorrow. The business world is unpredictable. But sometimes keeping up isn’t enough. Some of the top companies work to stay ahead of the curve.
A notable example of a company that failed to adapt is Apple, which missed the opportunity to license its Mac operating system. This ultimately allowed Microsoft to dominate the personal computer market.
Do You Maintain a Clear Focus?
The top performing businesses maintain a clear sense of purpose. While shifting business models or diversifying can be tempting, it’s important not to lose sight of your company’s core strengths. Always keep your business’s unique position in mind.
Have You Established a Strong Plan?
If you have a robust business plan in place, it will help you to navigate change. Always rely on realistic and measurable goals to guide your actions. When business owners focus on planning, they take the time to think critically and anticipate future challenges. When the market shifts, this offers them a sense of clarity. A solid plan allows you to stay grounded and proactive.
Are You Preparing for the Next Phase?
Knowing when and how to exit is an important consideration for any entrepreneur. Many business owners mistakenly wait until things are in decline to sell, but the most successful exits happen when the market is strong. Creating an exit strategy, even if it’s not immediate, is a savvy move.
A business broker or M&A advisor can help you navigate the process of selling your business from start to finish. Planning your exit from the outset ensures that when it’s time to move on, you can achieve financial success.
The world of entrepreneurship is full of challenges and uncertainties. However, by embracing technology, staying adaptable, maintaining focus, and planning strategically, you can position yourself for long-term success. Knowing when to exit gracefully at the right time will be the final testament to your success.
Business Brokerage Press, Inc.
The post Thriving in the Modern Business World appeared first on Deal Studio.

8 Benefits of Investing in A Franchise for Sale
When considering purchasing a business, the word franchise often comes up. A franchise allows you to own and operate a business that’s already part of a larger, established brand. It offers the unique opportunity to become part of a successful system that supports your growth. If you’re looking for a franchise for sale in Ontario or anywhere in Canada, here are 8 key benefits to consider!
Table of Contents:
Before diving into the process of buying a franchise, it’s important to understand why a franchise can be an excellent choice. A franchise involves purchasing the rights to operate a branch of a well-established brand with the backing of a franchisor. This partnership provides you with a proven business model, brand recognition, and ongoing support, helping you achieve success more easily than you would starting a business from scratch.
Support from the Franchise
Before purchasing a franchise in Canada, it’s important to understand how the support system works. Buying a franchise means gaining a dedicated support team to guide you through managing and operating the business. For first-time business owners, a franchise offers invaluable assistance, ensuring you’re equipped with the tools, training, and guidance to succeed. From the moment you sign the franchise agreement, you’ll receive hands-on support to help you navigate every step of the process.

Established Brand Name
One of the major benefits of buying a franchise in Canada is the opportunity to operate under a well-established brand. For instance, purchasing a franchise of a popular restaurant means you’re inheriting a strong brand reputation and customer base—recognition that you wouldn’t have to build from scratch. Your primary focus will be maintaining the franchise’s brand image and upholding its value in front of customers, rather than spending time on extensive marketing efforts.
Lower Risk
Starting a new business can be risky, requiring significant financial investment, marketing efforts, and planning, with no guarantee of success. However, buying a franchise gives you the benefit of an established business model. Franchises have already weathered the initial challenges and are positioned for growth. As a result, the risk of failure is generally lower compared to starting an independent business, making it a safer and more reliable option.
Comprehensive Training Programs
Once you sign your franchise agreement, you’ll undergo a comprehensive training program. This training covers everything from employee management to day-to-day operations, ensuring that you’re fully prepared to run your business. Many franchises also offer ongoing training to help you stay up to date on best practices and industry developments, boosting your confidence and expertise. This makes investing in a franchise a potentially safer and more structured way to enter the business world.
Marketing Assistance
Effective marketing is crucial to any business’s success, and when you purchase a franchise, the parent company provides valuable marketing support. Franchisors typically offer advertising materials, social media guidance, and promotional strategies to help you attract customers. This eliminates the need to start your marketing efforts from scratch, allowing you to focus more on operating your business with the support of their proven strategies.
Pre-Fabricated Business Plan
One of the most convenient aspects of buying a franchise is that you’re not starting from ground zero. With a franchise, you’re adopting a proven, well-established business plan that outlines everything you need to know for success. This business plan provides clear direction and saves you the time and effort of developing one on your own. With a structured blueprint in place, you can hit the ground running and ensure a smoother, faster path to success.
Community Connections
Franchises often have a strong community presence, and as a franchise owner, you’ll benefit from being part of this established network. Franchises frequently draw local customers who are loyal to familiar brands, and being involved in community events can help you build a loyal customer base. Additionally, being part of a franchise allows you to connect with other local business owners, fostering valuable relationships and increasing your business’s visibility in your community.
Flexibility
While franchises come with established systems and guidelines, they often provide flexibility in areas such as location, hours of operation, and staff management. This flexibility allows you to create a work-life balance that suits your lifestyle, giving you the freedom to spend quality time with family and friends while running a successful business. This flexibility can make owning a franchise not only rewarding but also enjoyable.

Conclusion
Investing in a franchise for sale is an excellent way to start your own business with the backing of an established and reputable brand. Franchisors provide valuable support and training to help you market and operate the business effectively. However, if you need additional guidance or expertise, consulting with professionals like Ontario Commercial Group can further enhance your success.
Read More
Selling Your Business? Consider These 5 Things First
Selling a business in Canada is one of the most challenging decisions a business owner can face. Whether driven by personal or professional reasons, deciding to sell your business is not a decision to be taken lightly. While the future may be uncertain, it’s essential to evaluate your current situation carefully before taking a significant step like selling your business in Ontario.
Table of Contents:
This process goes beyond merely transferring ownership—it requires a deep understanding of your motivations and meticulous attention to the legal and procedural details involved. In this blog, we’ll explore why selling your business can be a time-intensive journey and highlight the key considerations you should keep in mind throughout the process.
5 Things You Must Consider While Selling Your Business in Ontario

When selling your business in Ontario, there are several key factors to keep in mind. From accurately valuing your business to ensuring all legal aspects are covered, and from selecting the right broker to finding the ideal buyer—each step plays a vital role in a successful sale. Here are five essential points to consider:
1. Evaluate Your Business Value
Begin by determining the true value of your business. This requires in-depth market research, an analysis of current trends, and a comprehensive review of your financial performance—including assets, liabilities, revenue, and profit margins. A professional business broker can be invaluable in helping you arrive at an accurate valuation.
2. Organize Financial Records
Transparency is key. Prospective buyers will expect easy access to well-organized financial documents, such as tax returns, financial statements, and other relevant records. Ensuring these documents are accurate and readily available—and even undergoing an audit—can significantly enhance credibility and attract serious buyers.
3. Enhance Business Operations
Optimizing your operations can boost your business’s value and appeal. Streamline processes, improve efficiency, and clearly demonstrate your company’s financial health. By showcasing a well-managed operation and a solid plan for the future, you can instill confidence in potential buyers and facilitate a smoother transition post-sale.
4. Develop a Comprehensive Business Plan
A detailed business plan is essential when selling your business. It should outline your business model, market position, growth strategy, and competitive landscape. This plan not only serves as a roadmap for the future but also provides potential buyers with the insight they need to see the long-term value and potential of your business.
5. Seek Professional Guidance
Navigating the sale process can be complex. Engage with experienced professionals such as business brokers, M&A advisors, financial consultants, and legal experts. Their expertise will help ensure that your documentation is in order, that you understand every aspect of the sale, and that you negotiate the best possible deal.
By keeping these five points in mind, you can approach the sale of your business in Ontario with confidence and clarity, ensuring a smooth and successful transition.
Conclusion
Before taking the first step toward selling your business, it’s essential to clearly understand its value and financial standing. Knowing your business’s worth not only helps you set the right price but also instills confidence in potential buyers, who are keenly interested in its future growth and financial health. To ensure that all your documents and operational processes are in perfect order, consider seeking guidance from experienced M&A advisors. Every stage of the selling process is crucial, so meticulous preparation is key to a successful sale.
Read More
Recognizing Trouble in Your Business Before It’s Too Late

Businesses can face various challenges, and many issues that arise are not always immediately obvious. However, there are common signs to look for when a company is in trouble or headed in that direction. Recognizing these signs early is crucial, as they can help business owners make informed decisions about the future of their business.
Below are some key indicators that a company may be struggling:
Table of Contents:
Lack of Proper Focus
One of the most significant issues a business can face is a lack of clear focus. This could manifest as a lack of strategic direction or the failure to define specific goals. Without a clear focus, companies may struggle to stay competitive or fail to allocate resources effectively. Ultimately, this can lead to missed opportunities.
Poor Management
All businesses depend on good leadership. Poor management, whether it’s due to inexperienced leaders or ineffective decision-making, can severely impact the overall performance. Mismanagement may lead to inefficiencies, low employee morale, and issues with customer service.
Problems with Financial
Without strong financial controls, a business can quickly find itself in trouble. This includes things like inaccurate financial reporting and issues with cash flow management. This situation can result in mounting debt or an inability to sustain operations.
Loss of Key Employees or Customers
A business is only as strong as the people behind it. Losing a key employee with vital skills can create operational chaos. Similarly, losing important customers or clients can leave a company struggling to maintain profitability.
Failure to Adapt to Technology
Technology evolves rapidly. Companies that fail to keep up with technological advances risk falling behind. This can affect everything from customer satisfaction to the ability to stay competitive in the industry.
Quality Control or Operational Issues
Ongoing quality control problems, product defects, or inefficiencies in operations can tarnish a company’s reputation and decrease sales. Persistent operational issues often indicate deeper structural or management problems within the organization.
Legal or Governmental Problems
Legal disputes or not properly following government regulations can cause significant financial and reputational damage to a business. Whether it’s a lawsuit, or tax issues, these problems should never be ignored.
Changes in Dynamics
Market dynamics are constantly changing, and businesses that fail to adapt to shifts in customer preferences or an increase in competition may find themselves struggling to maintain relevance.
When a business begins to show signs of distress, owners often face two main options: fix the issues or sell the business. However, ideally the decision to sell should be made while the company is still performing well, not when it is already in trouble.
Waiting too long to right the direction of a business can not only reduce its value, but also limit an owner’s options. If you are concerned that your company may be facing difficulties, now is the time to consult with a professional business broker or M&A advisor. They can help assess the situation, guide you on preparing your business for sale, and assist in making the best decision moving forward.
Copyright: Business Brokerage Press, Inc.
The post Recognizing Trouble in Your Business Before It’s Too Late appeared first on Deal Studio.

Do’s and Don’ts of Selling A Business
Selling a business is a major decision and can be a complex process. As a business owner, you want to secure the best possible deal while ensuring a smooth transition for the new owner. To help guide you through this journey, we’ve compiled a list of essential do’s and don’ts for selling your business. By following these key steps, you can streamline the process and make the transition as seamless as possible.
Table of Contents:
Do’s of Selling A Business

1. Get Your Finances in Order
Before selling your business, it’s essential to ensure your finances are up to date. Potential buyers will thoroughly review your financial records to determine the value of your business. Having accurate and organized finances allows you to confidently present your company’s worth and secure the best selling price. Proper financial preparation also sets the stage for a smoother transition.
Tip: Hire a professional accountant or financial advisor to help organize your finances and make them appealing to potential buyers.
2. Plan Ahead
Selling a business is a long-term process, typically taking six to twelve months to complete, with two to three years of preparation required. It’s not something that happens overnight, and careful planning is crucial. By preparing well in advance, you’ll have control over the timing of the sale, fulfill all legal requirements, and meet the expectations of potential buyers.
Tip: Start planning to sell your business at least one to two years before you intend to sell. This gives you enough time to organize your finances and make any improvements necessary to secure the best deal.
3. Maximize the Value of Your Business
To get the best deal, it’s essential to maximize the value of your business. Focus on increasing profitability by diversifying your client base and generating repeat business. Develop a marketing plan with your team to boost top-line earnings, making your business more attractive to potential buyers.
Tip: Showcase the strong performance and profits of recent years. The more profitable your business is, the more valuable it will appear to potential buyers.
4. Maintain Confidentiality
While you want to sell your business quickly and at a good price, it’s important to maintain confidentiality throughout the process. Protect sensitive information by using a non-disclosure agreement (NDA) with all potential buyers. This ensures that your business’s private details remain secure during the sale process.
Tip: In addition to using an NDA, work with a reputable business broker, like Ontario Commercial Group, to discreetly market your business. Avoid publicly mentioning the business name while selling to prevent unnecessary attention.
Don’ts of Selling A Business

1. Don’t Rush the Process
It’s natural to want to sell your business quickly, but rushing the process can lead to costly mistakes. If you move too fast, you may end up with an unfavorable deal or sell to the wrong buyer.
Tip: Start planning early so you have ample time to filter potential buyers and evaluate offers that align with your goals. By taking your time, you can ensure the best possible outcome and avoid settling for less.
2. Don’t Overprice Your Business
Many business owners make the mistake of overpricing their business because they’re emotionally attached to it. However, it’s important to price your business based on its true market value, not on sentiment.
Tip: Set a realistic price using reliable valuation methods. Overpricing your business will likely result in it sitting on the market for too long, making it less attractive to potential buyers.
3. Don’t Underestimate the Importance of Accurate Valuation
Accurately valuing your business is one of the most challenging aspects of the sale process. Pricing too low may raise red flags with potential buyers, while an inflated price could scare them away.
Tip: Hire a professional business broker or investment banker to conduct a thorough valuation. They are well-versed in the different valuation methods and can help you establish an accurate price to present to buyers.
4. Don’t Misrepresent Your Business to Buyers
While it’s tempting to embellish certain aspects of your business to attract buyers, misrepresenting information can lead to serious legal issues down the road. It’s important to be transparent about both the strengths and weaknesses of your business.
Tip: Consult with a business advisor to learn how to present your business’s challenges to potential buyers without overemphasizing them. Being honest and upfront will help you build trust and avoid complications later on.
Conclusion
When a business owner decides to sell, the goal is often to complete the sale quickly and efficiently. However, there are important do’s and don’ts to consider to ensure the process runs smoothly and that you secure the best deal possible. By following the guidelines in this blog and partnering with professionals like Ontario Commercial Group, you can navigate the selling process with ease and confidence, making the experience hassle-free.
Read More
Post-Closing Steps for a Successful Transition

Once the deal is sealed and the closing is complete, many business owners might think their job is done. However, ensuring that the transition to the new owner goes smoothly is crucial not only for the business’ continued success, but also for protecting your own ongoing interests.
First and foremost, even after the sale, most sellers have some sort of vested interest in the new entity’s success. This can come in many forms. For instance, if you are due additional payments associated with the sale, it’s essential to ensure that the release of funds happens as expected. The buyer may also have issued you a note, representing a portion of the sale price that will be paid out over time. It’s in your best interest to ensure these financial arrangements are properly managed during the transition.
Another common scenario that impacts sellers after the closing occurs when they are also the landlord of the property that the buyer is now leasing. The lease agreement must be clear and mutually beneficial, as it will influence the buyer’s ongoing ability to operate successfully.
Taking the time to make sure your buyer is set up for success can help prevent any misunderstandings later on. It goes without saying that if there are troubles down the line, that can translate into headaches for sellers.
Additionally, if you recently sold a business, you may still have your name on the company letterhead or remain involved in the company in some other way. In this type of situation, your personal reputation could still be linked to the business, meaning that you have an obligation to ensure the buyer is capable of maintaining the same level of quality and integrity that you worked hard to build. This is not just about protecting your brand, but it is also about ensuring that the company’s legacy continues smoothly.
Lastly, your former employees are often dependent on the success of the sale. Many sellers have built close relationships with their staff over the years and care about their welfare. The decision to sell can have a significant impact on job security for these individuals so it’s vital to ensure the new buyer is the right fit for maintaining a stable work environment. It’s in everyone’s best interest to support a positive transition to ensure job security for former employees.
While the closing of a business sale is a major milestone, it’s far from the end of the process. By taking the time to manage the post-closing transition thoughtfully, you can help ensure the business continues to thrive, protect your financial interests, and leave a positive legacy.
Copyright: Business Brokerage Press, Inc.
The post Post-Closing Steps for a Successful Transition appeared first on Deal Studio.

What Are the Business Opportunities in Canada?
Canada offers a thriving environment for entrepreneurs, with a growing economy and an increasing demand for innovative services. Whether you’re located in Ontario, Toronto, or elsewhere in Canada, numerous business opportunities could be an ideal match for you. In this blog, we will explore some of the top business opportunities in Canada and how Ontario Commercial Group can help you take the first steps toward success.
Table of Contents:
Canada is an ideal place to launch a business. With a booming economy and a growing demand for innovative services, entrepreneurs in Toronto—and across Canada—have a wealth of opportunities to explore. Whether you’re based in Ontario, Toronto, or elsewhere in the country, you’ll find a diverse range of business ideas that could perfectly align with your vision. In the following discussion, we’ll explore some of Canada’s top business opportunities and explain how Ontario Commercial Group can help you realize your entrepreneurial dreams.
1. Furniture Rental Business
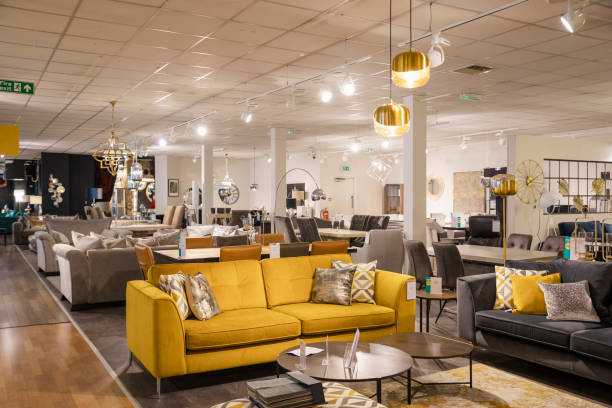
Furniture rental businesses have become increasingly popular among individuals seeking flexible, cost-effective solutions in Toronto. Many people prefer to rent furniture for short-term needs, whether it’s for setting up a new apartment or hosting an event. This presents a unique business opportunity, allowing individuals to enjoy high-quality furniture without the hefty upfront cost, using it only when necessary. You can offer various rental options, from sofas and beds to chairs, tables, and home decor. Starting this business is relatively low-cost, and as it grows, you can expand your inventory and attract a wider customer base. Ontario Commercial Group can assist you in acquiring an established furniture rental business or provide essential support if you choose to start this venture from scratch.
Furniture rental has become a popular business opportunity in Toronto, offering a flexible alternative for those who need high-quality furniture without the commitment of purchasing. Many individuals opt for short-term rentals when furnishing a new apartment or hosting an event, making this business model both practical and in demand.
You can offer a wide range of items—from sofas, beds, and chairs to tables and home decor. With a relatively low initial investment, you can gradually expand your inventory and client base as your business grows. Whether you’re interested in acquiring an established furniture rental business or starting one from scratch, Ontario Commercial Group is here to provide the support and guidance you need.
2. ICT
Technology is everywhere today, and businesses across all industries rely on exceptional digital services, making the ICT sector one of the top growth areas in Ontario. As one of the fastest-growing sectors in Canada, ICT encompasses services like web design, software development, and digital marketing. If you have a tech-savvy mindset, starting an ICT business could be an ideal opportunity. While you don’t have to be an expert, having a basic understanding of the field will certainly be an advantage. There will always be a demand for websites, apps, and tech support. Whether you’re interested in purchasing an established tech business or launching your own, a professional advisor can guide you through the process and help you thrive in the sector.

Today, technology is ubiquitous, and businesses increasingly depend on top-notch digital services, making the ICT sector a standout opportunity in Ontario. As one of Canada’s fastest-growing industries, ICT encompasses everything from web design and software development to digital marketing.
Even if you’re only somewhat tech-savvy, launching an ICT business is a smart move. You don’t have to be a tech expert—having a basic grasp of the concepts is enough to get started. The demand for websites, applications, and technical support is consistently high. Whether you choose to acquire an established tech business or build your own from the ground up, professional guidance can pave the way for success in this dynamic field.
3. Solar Energy Systems
Clean, green energy is a growing priority for many Canadians, with solar power being a key solution. The solar energy sector is booming in Ontario, particularly in sunny areas, offering lucrative business opportunities. You can start a business that provides solar energy systems, including the installation of solar panels on homes and businesses, as well as ongoing maintenance.
Starting a solar energy company is an excellent idea, especially as more people seek ways to reduce their high energy costs and lower their carbon footprint. At Ontario Commercial Group, we can help you find an established solar energy business for sale or provide expert guidance on how to build your own successful company in this rapidly expanding industry.
4. Personal Training Studio
In recent years, Canadians have increasingly prioritized health and fitness, making the personal training industry one of the most promising business opportunities in the country. Whether people are looking to lose weight, build strength, or improve flexibility, there’s a growing demand for expert guidance.

You can offer personalized one-on-one training, group classes, or even online programs to cater to different needs. With the help of the right professional, you can either find an existing gym or fitness business for sale or get support to create your own personal training studio. For fitness enthusiasts, this is a fantastic opportunity to turn a passion into a thriving business.
5. Upscale Hair Salon
Beauty services are always in high demand, as people are willing to invest in looking and feeling their best. Opening a high-end hair salon can be an excellent business opportunity, particularly in bustling cities like Toronto. You can offer premium services such as expert haircuts, colouring, and specialized treatments, catering to a discerning clientele.
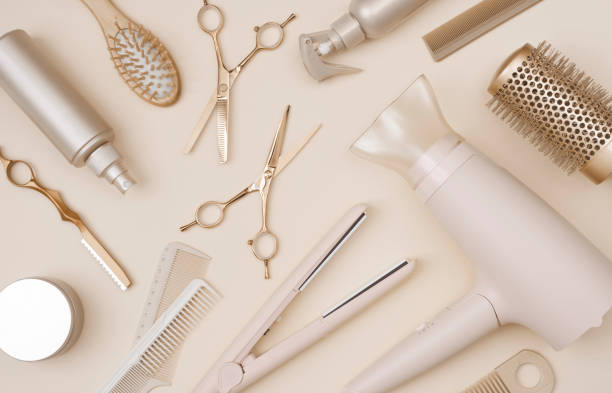
If you’re unsure about starting from scratch, consider exploring the best franchise opportunities for hair salons in Canada. High-end salons require skilled staff and a stylish, inviting atmosphere. With professional guidance, you can find an established salon for sale or secure the perfect location to open your own. With strong marketing and exceptional services, your salon will quickly become the go-to destination for clients seeking quality and luxury.
7. Robotic Welding Service
Technology is transforming industries across the board, and one of the most exciting advancements is the rise of robotics. Robotic welding is rapidly becoming a key component of manufacturing in Canada, offering faster, more precise results than traditional methods. This presents an excellent business opportunity in Toronto for those interested in the manufacturing sector.
While starting a robotic welding business can be a significant investment, the demand is strong, particularly in industries like construction, automotive, and heavy machinery. Ontario Commercial Group can assist you in finding established welding businesses for sale or provide guidance on launching your own venture with robotic welding services.
Conclusion
Canada offers a wealth of opportunities for aspiring entrepreneurs, from tech startups to health-focused businesses, beauty outlets, and franchise ventures. With continued economic growth, there is a constant demand for new services, making it an ideal environment for anyone looking to launch a business.
At Ontario Commercial Group, we specialize in helping individuals like you find the right business opportunities in Ontario. Whether you’re interested in acquiring an existing business or starting one from scratch, we provide the guidance and support you need. Business success requires commitment, market knowledge, and flexibility. With the right strategy and support, you can confidently pursue your entrepreneurial dreams in Canada. Let Ontario Commercial Group help turn your vision into a reality.
Read More
The Importance of a Professional First Impression

In today’s business world, effective communication is paramount, and the telephone remains one of the most essential tools for engaging with clients, prospects, and partners. Automated answering services, voicemail systems, or hold music can significantly impact your company’s image and customer satisfaction. Therefore, it’s important to ensure that the telephone is a productive sales tool rather than a hindrance.
Table of Contents:
The first interaction a caller has with your company is often through a phone call. This brief exchange, often lasting less than a minute, plays a pivotal role in shaping the caller’s perception of your business. That’s one reason why it’s crucial to use that first impression as an opportunity to create a positive and lasting impact. Below are some strategies to help you refine the way your business greets its callers.
Evaluate Your Office’s Phone Etiquette
To understand the true experience of a customer or client calling your office, consider making a test call. Just don’t reveal your identity. Have someone whose voice your staff does not recognize place the call while you listen in. This method allows you to assess the quality of your telephone service in an objective manner. During the call, listen for the following:
- A friendly and professional greeting, such as, “Good morning, [Company Name],” followed by the name of the employee and an offer to assist.
- A calm and helpful response to inquiries, or the offer to direct the caller to someone who can provide more information.
- Reasonable hold times, with an apology if the wait exceeds typical expectations.
This process is well worth your time, as it will give insights into how your staff handles calls and whether improvements are needed.
Assess Your Answering Service
If your business relies on an answering service, it’s vital to evaluate its quality. Conduct a similar test to the one mentioned above, but focus on how well the answering service represents your company. When evaluating this service, ensure that:
- The operator answers with your company’s name, rather than using a generic, impersonal greeting like, “May I help you?”
- The operator is well-versed in your business’s key details, such as hours of operation, employee names, and company policies.
- The message conveyed by the operator aligns with the information your business wants to relay to customers.
If the answering service fails to meet these standards, take the time to educate the provider on your expectations. There are many answering services out there. If yours is not meeting your standards, it might be time to make a switch.
Review Your Voicemail System
Your voicemail greeting is another key touchpoint for customers and clients. How it sounds can significantly impact their perception of your professionalism. Periodically listen to your voicemail message and ask yourself the following questions:
- Is the voice recording representative of your brand? Choose a voice that is clear, engaging, and professional, so that it strikes the right tone for your business.
- If your voicemail or call system includes background music or on-hold music, ensure that it is calming and unobtrusive. Many businesses make the mistake of choosing music that is grating and leads to someone hanging up before speaking to a member of your team.
A well-crafted voicemail message ensures that callers feel valued, even if they are unable to speak directly with someone.
Humanize Your Technology
There is no doubt that automated voicemail systems, speakerphones, and conference call capabilities are indispensable tools. However, it’s essential to remember that while these systems offer convenience, they can lack the personal touch that a human voice provides. The truth of the matter is that most people still prefer speaking with a real person.
Even if the employee who answers the phone is not the highest-paid member of your team, the human voice remains an essential element of your company’s identity. An empathetic, attentive response can leave a positive impression, contributing to a stronger relationship with your clients.
Today’s businesses must embrace the benefits of technology while remembering the importance of personal interaction. By regularly reviewing and improving your phone etiquette, you ensure that your business presents itself in the best possible way from the moment the phone rings.
Copyright: Business Brokerage Press, Inc.
The post The Importance of a Professional First Impression appeared first on Deal Studio.
Buying Business in Toronto: Top 5 Industries for Business Acquisition
Toronto is one of North America’s most dynamic business hubs, home to thriving sectors in finance, commerce, industry, and technology. For those looking to buy a business, Toronto offers a wealth of opportunities for both new owners and investors. As the home of the Toronto Stock Exchange and Canada’s largest business center, the city presents ideal conditions for business acquisitions. If you’re considering purchasing a business in Toronto, here are the top 5 industries to explore.
Best Industries For Business Acquisition
Table of Contents:
1. Financial Services and FinTech
Toronto is the financial capital of Canada. It is the second-largest financial industry in North America. Being home to a large number of financial institutions, including some of the largest banks in Canada, such as the Royal Bank of Canada, the Bank of Nova Scotia, and the Bank of Montreal, makes buying a business in Toronto in financial services and fintech beneficial. There are also plenty of insurance firms and investment companies, and in addition to that, the city has seen a rise in fintech startups that offer innovative digital financial solutions.
Why It’s a Good Investment:
- Strong financial hub: Toronto is the second-largest financial centre in North America, where you can get access to numerous banks, insurance firms, and investment companies.
- Emerging FinTech market: Toronto is noticing a growing adoption of digital banking, blockchain, and financial technological solutions such as mobile banking, blockchain-based payments, and robo-advisors.
- Global connections: Toronto’s proximity to both Canadian and U.S. markets makes it a strategic location if you are planning for the acquisition of a financial and fintech business.
2. Wholesale Trade
60% of all large wholesale companies in Canada run through Toronto. As Toronto is strategically located (being in proximity to the United States, which is Canada’s largest trading partner), it makes it a hub among Canadian cities and North America for trade. If you’re buying a business in Toronto in the wholesale trade industry, you can be assured of long-term growth and profits.
Why It’s a Good Investment:
- Strategic Location: With Toronto, you can get access to North American and global markets. It provides a competitive edge for wholesalers looking to import and export goods across North America and globally.
- Growing Consumer Demand: There is a consistent demand in Toronto for a wide variety of products that ensures the business buyer that there will be a stable customer base.
- Advanced Infrastructure for Wholesale Trade: Wholesale includes a lot of processes such as commerce, marketing, manufacturing, and engineering that undoubtedly need advanced infrastructure. Toronto has a well-established infrastructure with its highways, railways, and an international airport.
3. Healthcare and Life Sciences
Toronto and the Greater Toronto Area (GTA) are quietly establishing themselves as major hubs for the healthcare and life sciences industries. Toronto offers a promising venture for new startups in the life science industry as it offers great investment opportunities and prospects for collaboration. If you are buying a small business in Canada, Toronto has many hospitals, which include Sunnybrook Hospital, Hospital for Sick Children (Sick Kids), and Toronto General Hospital, which makes a great opportunity for buyers.

Why It’s a Good Investment:
- Aging population: The rising number of seniors in Canada is creating demand for medical services. There is a high demand for elder care and pharmaceutical solutions.
- Cutting-edge research: Toronto’s healthcare sector is bolstered by leading research that is successfully bringing research stakeholders together.
- Stable and essential: Healthcare is one of the most stable industries in Canada and worldwide, remaining in demand regardless of economic cycles.
4. Technology and Startups
Studies show that Toronto is competing at the same level as other booming tech cities in North America and around the world. This is because of the exponential growth of the tech sector and talent in Toronto. Also, the city has seen a large influx of venture capital investments, making it a booming sector for tech industries. From software development to artificial intelligence and cybersecurity to blockchain, Toronto is becoming a hub for technology, and business buyers interested in technological businesses buying business in Ontario is beneficial.
Why It’s a Good Investment:
- Strong growth prospects: As of 2024 and beyond, Toronto’s tech industry is expected to continue expanding, which shows a great demand for digital solutions, creating a great opportunity for business buyers.
- Access to talent: Toronto has a high concentration of skilled workers, which includes top graduates, which makes technology startups a huge success and creates growing demand in Toronto.
- Government support: The Canadian government is taking a lot of initiatives, such as grants and tax incentives, to make Toronto an attractive location for tech investments.
5. Hospitality and Food Services
Toronto is undoubtedly a great global tourist destination with a wide variety of restaurants and a hospitality scene. Also, its vibrant landscape has made it emerging for sectors such as food tech—a convergence of food, agriculture, and technology. As consumers worldwide are becoming more health-conscious and sustainability-driven, food tech services and hospitality are rapidly growing in Ontario hence Buying A Business In Ontario becomes a profitable venture.
Why It’s a Good Investment:
- Growing Tourism: With international travel booming, tourism-related businesses such as hotels, restaurants, and event services are seeing strong demand in Canada.
- Growing Consumer Demand: As consumers are becoming more health-conscious and tech-savvy, it’s making food tech in growing demand.
- Diverse culinary scene: Toronto’s multicultural environment makes its food industry one of the most diverse and innovative in North America.
Conclusion

Buying a business is a significant decision, and it’s best to make your investment in an industry that you truly relate to. Toronto’s strategic location offers immense opportunities for buyers seeking a profitable venture to acquire. If you are searching for an industry that is highly profitable and offers long-term growth potential, choose one among the five industries discussed in this blog.
Ontario Commercial Group is a renowned brokerage service in Ontario, Canada. If you are looking for brokerage assistance for buying and selling a business, choose Ontario Commercial Group experts to navigate the process with ease!
Read More
The Risks of Under-Reporting Income for Business Owners

One of the most critical questions for prospective buyers, investors, and lenders is understanding a business’s true income. However, it should come as no surprise that the party most invested in uncovering this information is the Internal Revenue Service (IRS).
Table of Contents:
Why is determining a business’s real income so difficult? While financial records should provide a clear picture, business owners often engage in practices ranging from minor adjustments to outright fraud in order to minimize reported income and reduce their tax liabilities. In fact, the IRS estimates that two out of three business owners under-report their income.
Even if a business owner somehow evades detection, this dishonest reporting can create significant challenges when it’s time to sell. Business owners, even those not yet considering a sale, should start preparing by presenting their company as a profitable, legitimate enterprise. A buyer will scrutinize not just the numbers, but also the history behind them. That means that any discrepancies between the books and the tax returns will be a red flag. A fresh narrative about the business’ potential is unlikely to convince a buyer, who will be more interested in tangible evidence of consistent and legitimate profitability.
Here are some steps for business owners to position their business favorably when the time to sell comes:
Think Long-Term
Instead of focusing on short-term tax savings, business owners should prioritize showing long-term profitability. Buyers are looking for businesses that demonstrate consistent, strong performance over a period of time. By ensuring your records reflect maximum profits for each quarter, you can create a more attractive picture for potential buyers. The more stable and profitable your business appears, the easier it will be to justify a higher asking price.
Review and Adjust Past Records
It’s important to take a step back and carefully review past financial statements. If your business has experienced growth, but that growth isn’t reflected in your tax returns or financial reports, now is the time to adjust those numbers. Go through the past few months of records and adjust them to present a clearer, more accurate picture of the business’ financial health. This work will not only improve your credibility with buyers but also set a more favorable stage for future negotiations.
Reconstruct Historical Financials
If necessary, look back even further to reconstruct your financial records in a way that reflects the true profitability of your business over a more extended period. This process involves carefully revisiting past transactions, correcting any under-reported income, and ensuring that your financial history aligns with the real growth of the business. Although it may require additional effort, having accurate financial records that reflect the business’ legitimate success will go a long way toward building trust with potential buyers and lenders.
List Tax-Deductible Expenses and Benefits
As part of your effort to present a more truthful financial picture, it’s crucial to itemize all tax-deductible expenses, such as salaries, fringe benefits, and other perks that are allowed by the IRS. These items provide ongoing value to the business and should be clearly listed in your records. Doing so can help increase the perceived value of your business. Buyers will appreciate knowing the business is efficiently managing its finances while taking full advantage of available deductions.
By addressing these areas, you can not only improve the appeal of your business to potential buyers but also enhance your chances with lenders and investors. Most importantly, truthful financial reporting will keep the IRS focused on someone else’s business.
Copyright: Business Brokerage Press, Inc.
The post The Risks of Under-Reporting Income for Business Owners appeared first on Deal Studio.