


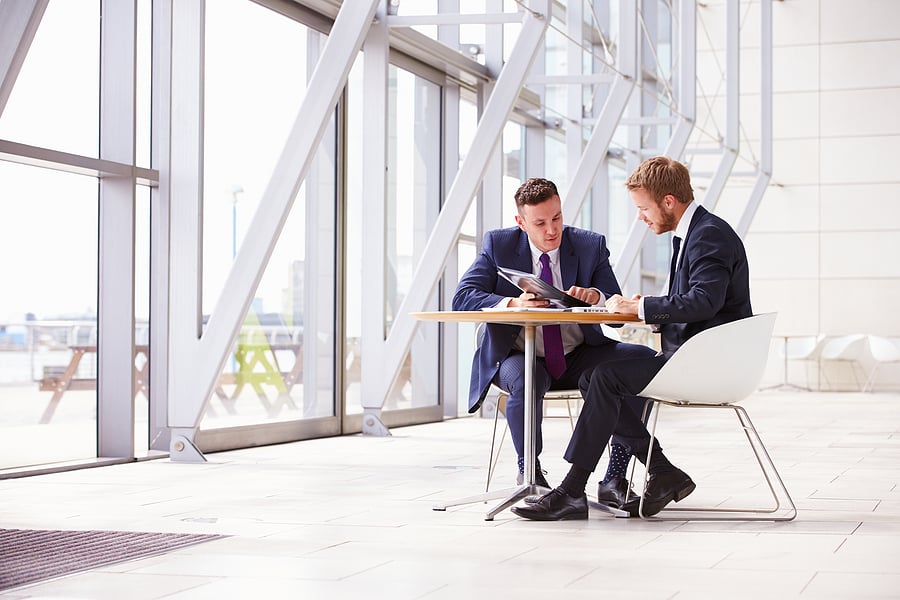
Why Every Business Partnership Needs a Written Agreement
Starting a business with a friend, colleague, or someone in your family can feel uncomplicated at first. Because a level of trust already exists, business owners often make the mistake of skipping a formal partnership agreement. Unfortunately, even strong relationships can run into headaches when expectations are not clear. You never know when disagreements can arise over issues such as responsibilities or future decisions.
Table of Contents:
Why Have a Partnership Agreement?
A partnership agreement is one of the most important documents in a business. It creates a clear understanding between all parties involved. These agreements help prevent misunderstandings before they turn into larger problems.
A partnership agreement is an important tool in your arsenal because it protects both the business and the people behind it. The goal is to have all of your expectations and procedures in writing from day one
What Should be in Your Agreement?
One of the main purposes of a partnership agreement is to begin with a foundation of how the business operates. This includes putting in writing the ownership percentages, profit distribution, and strategies for handling losses. While these topics may seem obvious at first, assumptions can quickly lead to conflict if they are not clearly documented. When everything is written down, it creates a necessary level of accountability. Partners will share the same understanding of how the business is structured.
The agreement should also outline each partner’s role and responsibilities. In many partnerships, one person may oversee operations while another focuses on finances and/or growth strategy. Without clearly assigned duties to the people involved, confusion and resentment can develop over time. Even if responsibilities do evolve and change as your business grows, starting with clear expectations maintains a degree of alignment.
Transparency for Financial Matters
Financial matters are another critical part of any partnership agreement. Money is often one of the biggest sources of tension in business relationships, especially if the partners have different expectations regarding compensation or how to invest funds. A strong agreement should explain how profits will be divided. It will also address how business expenses will be handled.
What happens if additional funding becomes necessary down the line? At some point you might need money to support the growth of your business. The agreement should explain whether partners are expected to contribute additional money and how those contributions will affect operations.
Outline How Decisions are Made
You and your partners will eventually not agree on an aspect of your business. Some partnerships operate with equal voting rights, while others assign different roles. Establishing a process for making major business decisions now can help circumvent disputes later. This may include outlining how votes are conducted and how decisions are approved. You will want a clause that addresses potential disagreements.
Expecting the Unexpected
A good partnership agreement should also prepare for unexpected events. While no one likes to think about difficult situations, planning ahead can protect the business in the long run. The agreement may include procedures for adding new partners or handling an owner’s departure.
Creating Your Agreement
Working with an experienced attorney or brokerage professional is often the best option, as templates are likely not detailed enough. A properly drafted agreement can address details that business owners may overlook. You can then rest assured that your document complies with applicable laws.
Taking the time to create a thorough partnership agreement may feel tedious in the beginning, but it can save significant stress later on. A well-structured agreement will allow business partners to focus on growth and operations with a greater level of confidence.
Copyright: Business Brokerage Press, Inc.
monkeybusinessimages/BigStock.com
The post Why Every Business Partnership Needs a Written Agreement appeared first on Deal Studio.
Read More
The Advantage of Buying an Existing Business
Most people think of starting a business from scratch, developing an idea, building a company from the ground up. Starting from scratch, however, has its disadvantages including – developing a customer base, marketing the business, hiring employees and creating cash flow … without any history or reputation to rely on.
Table of Contents:
To avoid these challenges, buying an existing business may prove to be the better solution. Buying an existing business has its advantages – including, but not limited to:
The Business Is Established.
An existing business is a known entity. It has an established and historical track record. It has a customer or client base, established vendors, and suppliers. It has a physical location with furniture, fixtures, and equipment in place. The term “turnkey operation” may be overused, but an existing business is just that, and more. New franchises may offer a so-called turnkey business opportunity, but it ends there. Start-ups are starting from scratch with all the disadvantages stated above.
The Business Has Existing Relationships.
In addition to the existing relationships with customers or clients, vendors, and suppliers, most businesses also have experienced employees who are valuable assets to the company. A buyer may already have established relationships with banks, insurance companies, printers, advertisers, professional advisors, etc., but if not – the existing business/owner does, and they can readily be transferred to the buyer as part of the acquisition.
The Business Isn’t “A Pig in a Poke”.
Starting a new business is just that: “a pig in a poke.” No matter how much research, time, and money you invest, there’s still a big risk in starting a business from scratch. An existing business has a financial track record along with established policies and procedures. A prospective buyer can see the financial history of a business – when sales are high and low, what the true expenses of the business are, and how much money an owner can make, and more. Also, in almost all cases, a seller is more than willing to stay on to teach and work with a new owner – sometimes free of charge.
An Existing Business Comes with A Price and Terms.
As stated above, an existing business has everything in place. The business is in operation and typically has an established selling price. Opening a new business from scratch comes with a great degree of uncertainty and can become a proverbial “money pit”. When purchasing an established business, a buyer knows exactly what he or she is getting for their money. In many cases, a seller is also willing to take a reasonable down payment and then finance the balance of the purchase price.
The “Unwritten” Guarantee.
By financing the purchase price, a seller is saying that he or she is confident that the business will be able to pay its bills, support the new owner, plus make any required payments to the seller.
Copyright: Business Brokerage Press, Inc.
monkeybusinessimages/BigStock.com
The post The Advantage of Buying an Existing Business appeared first on Deal Studio – Automate, accelerate and elevate your deal making.